The Federal Government Enters the Investors’ Arena
For most of modern American economic history, Washington avoided acting like an investment fund. The federal government regulated companies, taxed them, bought goods and services from them, provided loans and subsidized activities it considered strategically important. Direct ownership stakes in private companies, however, were generally reserved for exceptional situations such as development finance, financial crises or projects of vital national interest.
That boundary is now beginning to fade. Since January 2025, the U.S. government has announced transactions worth a combined $27.7 billion across 39 operations involving direct ownership or equity-like instruments. The deals cover critical minerals, semiconductors, manufacturing, infrastructure and other sectors considered essential to the country’s economic competitiveness and security.
Economic Security Is Becoming National Security
The reasoning behind this shift is clear. In an increasingly tense global economy, supply chains have become a national-security concern. China controls significant portions of critical-mineral processing and plays a dominant role in several strategic supply chains.
Governments around the world are also using subsidies, state-owned companies, export restrictions and other forms of intervention to strengthen their industrial position. In that environment, U.S. government capital invested alongside private money can help launch important projects that markets might not finance on their own.
But strategic justification cannot become a blank check for unlimited intervention.
State Ownership Must Remain the Exception
Not every industrial challenge requires the federal government to appear on a company’s shareholder register. Public administrations are not designed to operate like conventional investment managers, and taxpayer money should not replace private financing when the market can reasonably deliver the same result.
If Washington decides to assume equity risk, the rationale must be clear, exceptional and governed by consistent rules.
Before making a direct investment, officials should determine whether the objective could be achieved through less intrusive mechanisms, including:
- a loan;
- a government guarantee;
- an offtake agreement;
- a public-procurement contract;
- a conventional subsidy.
Direct government ownership should be considered only when these tools are insufficient. Any such decision should also follow rigorous due diligence concerning the company, its valuation and the specific strategic benefit for the government.
Every Public Investment Needs an Exit Plan
A government that enters a company’s ownership structure must also know when and how it will leave. An exit strategy cannot be postponed, particularly when Washington is simultaneously acting as shareholder, regulator, customer and policymaker.
The government must establish in advance the conditions under which public capital will eventually be replaced by private investment. Without a credible exit plan, a temporary state holding can turn into a permanent and difficult-to-justify presence.
Critical Minerals Are Testing the New Industrial Policy
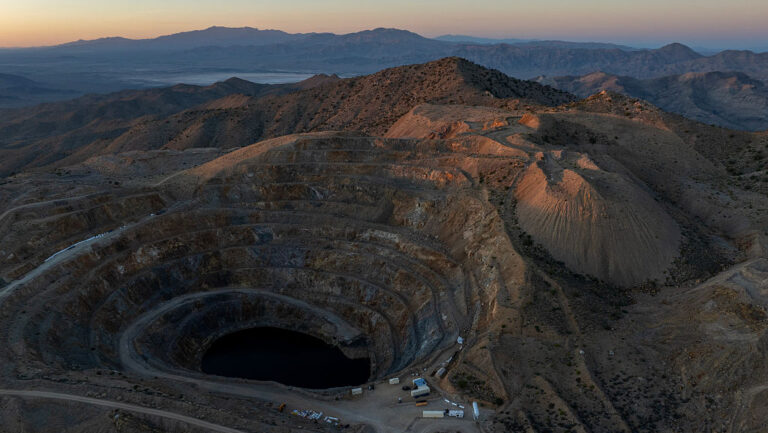
Recent transactions in the critical-minerals sector illustrate how quickly the boundaries of government intervention are changing. The Pentagon’s investment in MP Materials combined equity with loans, price support and an offtake agreement.
In another case, the Department of Energy received warrant rights in Lithium Americas and its Thacker Pass joint venture as part of a restructuring designed to reduce risks for taxpayers.
Public equity is therefore becoming an additional instrument of American industrial policy, used alongside loans, guarantees and purchasing agreements. That makes strong selection, valuation and governance standards more important—not less.
Foreign Investments Create Additional Risks
The challenges become more complex when Washington invests in companies based outside the United States, particularly when such investments are repeated. If American taxpayers’ money is directed toward foreign firms, the government should demand governance standards comparable to those applied to U.S.-listed companies.
That should include:
- independent oversight of management;
- credible audit arrangements;
- scrutiny of related-party transactions;
- protection against unjustified dilution;
- transparent financial reporting;
- clear remedies when agreed standards are violated.
These requirements do not mean that every foreign company receiving U.S. government financing should automatically become subject to the full reach of American corporate or securities law. Different jurisdictions have different legal structures and corporate systems.
But differences between legal systems do not justify weak protections for public investors. American capital should come with credible safeguards, just as it would in any investment made by a sophisticated institutional investor.
Rules Should Not Be Reinvented for Every Deal
Washington has already secured meaningful protections in some transactions. In its investment in Canadian company Trilogy Metals, the U.S. government negotiated the right to designate an independent third-party director and, as long as it retains its stake, a non-voting board observer.
It also obtained consent rights over certain substantial increases in indebtedness.
The question is why such protections should be negotiated from scratch in every transaction. As federal equity investments become more common, agencies should establish a baseline framework for investments in foreign companies.
Those rules should remain flexible and adaptable to the circumstances of each deal. They should not mechanically export U.S. securities law overseas. At a minimum, however, they should address five areas: independent board and audit oversight, related-party transactions, protection against dilution, financial disclosure and government rights when governance standards deteriorate.
Protecting Taxpayers Also Means Preserving Fair Competition
Strong governance standards protect more than taxpayers. They also create fairer conditions for American companies.
A U.S. company listed on an American exchange must comply with demanding rules on disclosure, auditing and corporate governance. It would be contradictory for a foreign competitor to receive preferential U.S. taxpayer capital while facing substantially weaker safeguards over the management of that capital and the company itself.
Clear rules also benefit the recipients of public investment. Companies can understand from the outset what accepting federal capital entails, while transactions become less vulnerable to one-off political bargaining.
Transparency Can Shield Industrial Policy from Favoritism Claims
An investment with transparent objectives, valuation criteria and safeguards is easier to defend before Congress, auditors, future administrations and taxpayers.
By contrast, a deal negotiated hurriedly and behind closed doors can be portrayed as a favor to a politically connected company. A future administration could then unwind or restructure it with relative ease.
The durability of industrial policy depends not only on the strategic purpose of individual projects, but also on how they are selected, valued and governed.
The Fundamental Question: Why Should the State Own the Company?
The debate over governance should not obscure the central issue: when is it justified for the U.S. government to own companies?
The test should be demanding. Public ownership should address a specific problem that less intrusive instruments cannot solve. In addition, the expected public return should adequately compensate taxpayers for the additional risk they are being asked to bear.
The Trump administration has brought equity ownership back to the center of economic statecraft and geopolitical influence. The United States is already a shareholder in companies at home and abroad.
The challenge is no longer whether the government will invest, but whether it will do so with discipline.
That requires rigorous due diligence before every transaction, clearly defined public objectives, transparent criteria for selecting recipients, a credible exit strategy and governance protections proportionate to the risks borne by taxpayers.
Washington should not become a political patron distributing capital to favored companies. Nor should it act as a passive shareholder, accepting terms that an experienced private investor would reject.
If the U.S. government wants to invest like an institutional investor, it must manage its holdings by the same standards.